Key Takeaways
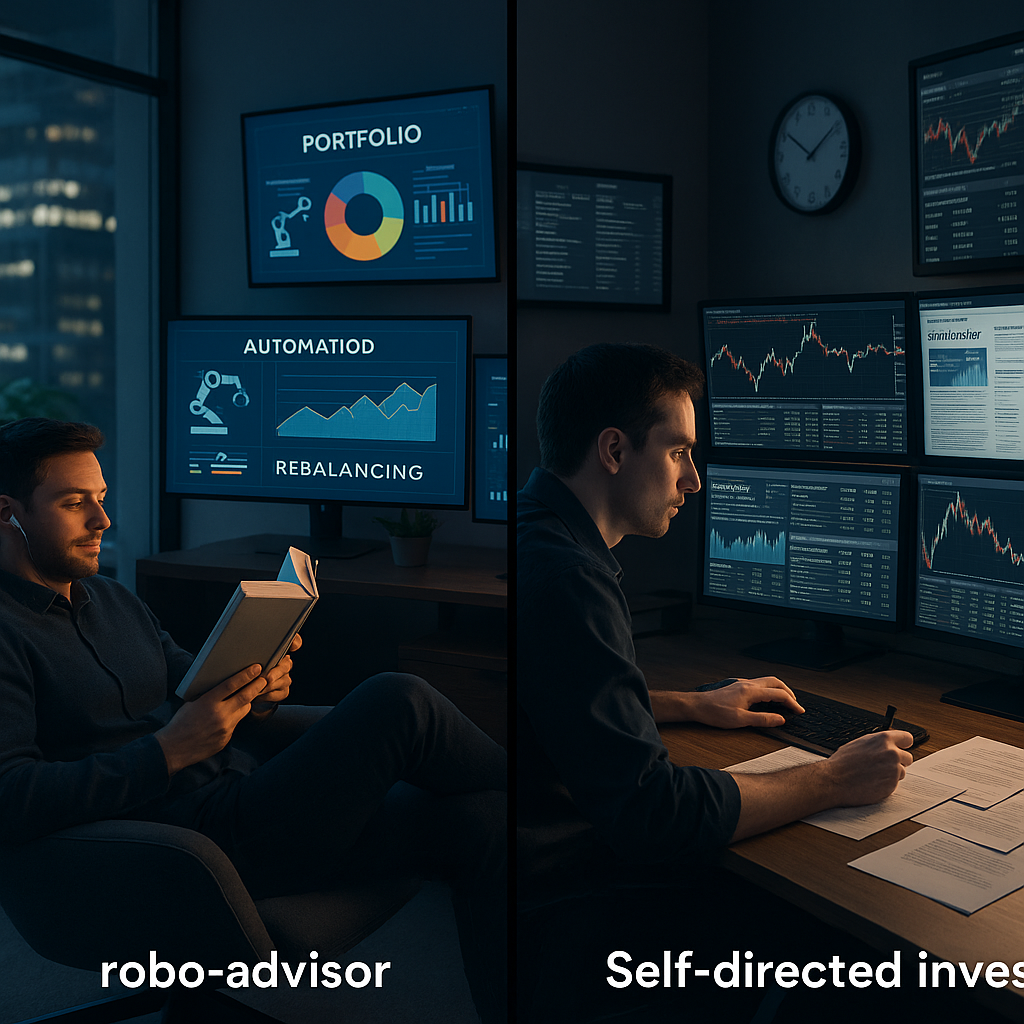
- Robo-advisors and self-directed portfolios provide distinct approaches to investment management, each with unique benefits and trade-offs related to cost, control, and personalization. Understanding these differences is essential for making informed decisions that align with your financial goals and comfort level.
- Automated investing significantly reduces management fees. Robo-advisors generally charge lower fees than traditional advisors or brokerage-managed accounts, making them appealing for cost-conscious investors seeking efficient, hands-off portfolio management.
- Full control resides with self-directed portfolios. Managing your own portfolio gives you complete freedom and flexibility over every investment decision, but demands time, research, and confidence to navigate the markets effectively.
- Self-directed strategies offer unmatched customization. Investors can tailor holdings to match personal preferences, ethical values, or specific tax situations. In contrast, robo-advisors often limit customization options to risk tolerance and broad objectives.
- Robo-advisors automate complex tasks for convenience. These automated platforms streamline portfolio rebalancing, tax-loss harvesting, and allocation adjustments. This reduces the burden of ongoing management and minimizes the behavioral mistakes common to busy or newer investors.
- Self-directed investing requires persistent engagement. To make the most of this approach, investors must remain well-informed about market trends, continuously monitor performance, and adapt rapidly to shifting circumstances and goals.
- Cost comparison goes beyond simple fee structures. While robo-advisors minimize direct management costs, additional expenses may arise from fund-level fees (for example, about 0.03% to 0.17% on average for the Betterment Core portfolio) or minimum account requirements. Self-directed accounts can appear low-cost but may incur hidden costs due to frequent trading, research tools, or the acquisition of specialized assets.
- Choosing between tech-driven guidance and deep personalization is a central decision. Robo-advisors leverage algorithms to create portfolios tailored to your financial profile, appealing to those who value simplicity and objective recommendations. Self-directed investing empowers you to pursue niche, ethical, or complex strategies that algorithms may not accommodate.
By thoroughly exploring the benefits and challenges of robo-advisors versus self-directed portfolios, you can better determine the investment approach that matches your style, ambitions, and appetite for hands-on involvement. Let’s dive deeper into these differences to help you optimize your investment management strategy.
Introduction
Selecting the right approach to manage your investments involves more than just crunching numbers. It requires weighing the balance of control, convenience, and customization that suits your unique financial aspirations. Robo-advisors offer the promise of effortless, algorithm-driven investing with attractively low fees. On the other hand, self-directed portfolios put you in the driver’s seat, allowing you to fine-tune every aspect of your holdings.
Understanding the trade-offs between these strategies is crucial for investors who want to keep costs in check, maintain the right degree of control, and ensure their investments accurately reflect personal goals and values. In the following sections, we’ll break down how these approaches compare across key areas such as fees, control, flexibility, and long-term potential.
Understanding the Cost Structure
Taking a closer look at the true costs involved is central to selecting the right investment path. Both robo-advisors and self-directed accounts tout affordability, but the details matter.
Stay Sharp. Stay Ahead.
Join our Telegram Channel for exclusive content, real insights,
engage with us and other members and get access to
insider updates, early news and top insights.
 Join the Channel
Management Fees and Expenses
Robo-advisors typically charge annual management fees between 0% and about 0.35% of assets under management on their basic plans. For example, Wealthfront charges 0.25% a year, Betterment charges 0.25% once you deposit $200 a month or hold $24,000, and $5 a month otherwise, Fidelity Go charges nothing under $25,000 and 0.35% above, and Schwab Intelligent Portfolios charges no advisory fee, with a $5,000 minimum. These fees generally cover portfolio construction, systematic rebalancing, and basic tax-loss harvesting.
Self-directed investing, by comparison, can be especially cost-effective for disciplined individuals. Top online brokerages like Fidelity and Charles Schwab now provide commission-free trades for stocks and ETFs. However, investors should also factor in fund expense ratios, which for popular index funds usually fall between 0.03% and 0.25%. These ongoing costs can add up, especially for larger portfolios or actively traded accounts.
Hidden Costs and Additional Services
A broader view reveals hidden or supplemental expenses in both models:
For robo-advisors, you may encounter:
- Additional fees for access to human advisors (often 0.15% to 0.40% extra)
- Balance thresholds for some features: Schwab Intelligent Portfolios offers tax-loss harvesting only from $50,000, at no extra fee
For self-directed portfolios, possible costs include:
- Trading spreads and bid-ask differences, which impact high-frequency traders
- Subscriptions to advanced research tools (typically $20 to $200 per month)
- Software for tax optimization or portfolio analytics
- The value of your own time spent monitoring and managing investments
These layered costs demonstrate the need to assess the full expense picture when choosing your investment route.
Control and Decision-Making
Examining how much control you desire is another major factor in finding your ideal investing fit.
Portfolio Management Autonomy
Self-directed investors enjoy ultimate autonomy. This includes:
- Selecting individual securities (stocks, bonds, funds)
- Choosing when and how often to trade
- Implementing specific risk-control or hedging strategies
- Setting your own rebalancing schedule
Robo-advisors, by contrast, use algorithms to automate these decisions. While you can usually adjust your risk profile or investment objectives, the ongoing management (such as asset selection and allocation changes) is handled by the platform with minimal need for your input.
Market Response Flexibility
One of the biggest advantages of self-directed portfolios is the ability to act swiftly on market developments or new opportunities, such as reacting to breaking news, capturing emerging trends in sectors like technology or healthcare, or capitalizing on geopolitical shifts that affect international investments. This real-time responsiveness can be valuable, especially for investors pursuing tactical or opportunistic strategies.
Robo-advisors prioritize discipline and objectivity. Their algorithm-driven rules limit impulsive decisions and emotional responses, instead maintaining a steady course through regular rebalancing and allocation reviews, even during volatile market environments. This is particularly powerful for investors who might otherwise succumb to panic selling or irrational exuberance.
Customization Options
Your ability to tailor an investment portfolio is a pivotal aspect of the selection process.
Investment Selection Range
Most robo-advisors concentrate on providing:
- Diversified, low-cost ETF portfolios
- Select ESG (Environmental, Social, Governance) options for responsible investing
- Smart-beta strategies targeting specific risk or return factors
- Limited exposure to direct stock positions or alternative assets
With a self-directed account, the universe of investments expands:
- Individual stocks, corporate and government bonds
- Complex securities like options, futures, or derivatives (futures are offered by some brokers, such as Schwab)
- Real estate investment trusts (REITs) and other alternative assets
- Niche sector and international ETFs
- Emerging market funds or commodity-linked investments
This broader selection makes self-directed investing appealing to those wanting to build specialized, highly diversified, or ethically aligned portfolios.
Portfolio Tailoring Capabilities
Robo-advisors have evolved to offer a higher degree of customization than in the past. Many now support:
Stay Sharp. Stay Ahead.
Join our Telegram Channel for exclusive content, real insights,
engage with us and other members and get access to
insider updates, early news and top insights.
Join the Channel
- Goal-driven portfolios for retirement, major purchases, or education savings
- Tax-loss harvesting to reduce tax exposure
- Income-focused or capital appreciation strategies
- Some platforms allow for faith-based, environmental, or social screens
Self-directed investors push customization even further, with control to:
- Fine-tune sector weights or exclude certain industries entirely
- Avoid specific companies based on ethical or risk considerations
- Employ advanced options or hedging strategies
- Dynamically adjust allocations to reflect evolving personal priorities or changing market outlooks
Performance Considerations
Evaluating the historical performance and risk management of each approach is critical, as both return potential and downside protection matter for long-term wealth building.
Historical Returns Analysis
Robo-advisors build diversified portfolios of ETFs, so their returns follow the markets they hold, in good years and bad ones, and past returns do not guarantee future results.
For self-directed portfolios, outcomes display a much wider range. While some disciplined investors beat the major indices, research on individual investors points the other way: in a study of 66,465 brokerage households from 1991 to 1996, the average household earned 16.4% a year against 17.9% for the market, and the most active traders earned 11.4%. Psychological biases, timing errors, and lack of diversification are common pitfalls.
Risk Management Approaches
Robo-advisors excel at systematic risk management, consistently applying practices such as:
- Rebalancing to maintain target asset allocations
- Diversifying across asset classes and regions
- Conducting tax-loss harvesting to maximize after-tax returns
- Investing recurring deposits automatically, a form of dollar-cost averaging that can help manage risk
Self-directed investors carry full responsibility for risk control, which may include:
- Determining appropriate position sizes for each holding
- Using stop-loss orders or hedging tools to limit losses, keeping in mind that a stop order becomes a market order and may fill at a different price in a fast-moving market
- Actively monitoring news, macro trends, and individual asset risks
- Scheduling regular portfolio reviews and rebalancing
In industries like healthcare and finance, investors may also need to consider unique sector risks, regulatory changes, or global events. For example, a self-directed investor focused on biotech stocks must stay updated on FDA approvals and research breakthroughs, while someone targeting financial technology investments needs to monitor both technical innovation and shifting regulatory landscapes.
Time Investment and Expertise Required
Understanding the depth of knowledge and time required is essential before committing to any investment approach.
Learning Curve Comparison
Most robo-advisor solutions are accessible with very little prior investment knowledge. Steps include:
- Articulating your financial goals and risk tolerance
- Setting up your account; Fidelity Go, for example, says you can get your personalized investment strategy in just a few minutes
- Reviewing automated reports and progress occasionally
Self-directed investing demands ongoing education:
- Mastering fundamental and technical analysis techniques
- Staying current on economic news, market research, and company developments
- Becoming proficient with trading platforms and analytical tools
- Continuously refining risk management and diversification strategies
Ongoing Time Commitment
Time investment diverges sharply between the approaches.
- Robo-advisors generally require only occasional progress reviews or minor adjustments.
- Self-directed investors spend their own time, every week, actively researching, monitoring, and trading. If you’re engaged in frequent trading or closely tracking specific sectors like technology or consumer goods, that number climbs.
Choosing Your Investment Path
Deciding which model best fits your needs involves an honest assessment of your goals, personality, and available resources.
Investor Profile Assessment
Robo-advisors are ideal for you if you:
- Prefer automated management and hands-off investing
- Want professional-grade diversification without heavy lifting
- Have straightforward financial goals, such as retirement or general wealth accumulation
- Value simplified, objective portfolio recommendations
Self-directed investing suits those who:
- Enjoy researching markets and identifying investment opportunities
- Seek complete control over portfolio composition and trading decisions
- Have specialized strategies or values that aren’t easily addressed by algorithms
- Want maximum flexibility to quickly adjust holdings in response to rapidly changing conditions
Hybrid Approaches
Some investors blend both strategies, such as:
- Adopting a core-satellite model (using robo-advisors for the portfolio core and actively managing a portion for targeted strategies)
- Segregating goals (for example, retirement accounts managed by robo-advisors and brokerage accounts managed directly)
- Gradually transitioning (starting with robo-advisors before moving to self-directed as confidence and experience grow)
Conclusion
The decision between robo-advisors and self-directed portfolios ultimately comes down to your unique blend of cost sensitivity, desire for control, need for customization, and willingness to invest in your own financial literacy. Robo-advisors offer a streamlined, automated path that helps minimize emotional missteps, lower costs, and simplify the investment process. This can be a strong fit for those who value efficiency and professional oversight with minimal time commitment.
Self-directed investing, in contrast, can suit those ready to invest significant effort into gaining expertise, staying engaged with the markets, and crafting truly personalized strategies. Its flexibility appeals to hands-on investors with niche interests or strong convictions.
A hybrid model can draw on the strengths of both approaches: convenience and control, discipline and flexibility, automation and personalization.
Looking ahead, the investment landscape will continue to evolve as technology advances and new financial tools emerge. Whether you choose hands-off automation, hands-on management, or a blend of both, the choice works best when it rests on clarity, consistency, and informed decisions that align with your personal financial journey.
This article is for educational purposes only and is not financial advice: all investing involves risk, including the possible loss of the money you invest, and past performance does not guarantee future results.

Leave a Reply